
Choosing a core system is a technology decision that reaches across an insurance company. Policy administration, billing, and claims affect pricing, cash flow, customer service, and regulatory reporting. Some platforms bring these functions together; others require separate systems and integrations. Leaders need to assess vendor financial health, implementation support, and long-term fit, not just features and price.
Cloud delivery and AI add more questions to the decision. For property and casualty (P&C) insurers, the challenge is to distinguish useful capabilities from marketing claims while choosing a migration path the business can manage.
Decide Your Modernization Path First
Before meeting vendors, agree on the change you need. Building your own platform offers control but demands specialist talent and time. Buying a packaged platform can reduce development work, though it introduces vendor dependencies. Upgrading the current system may be less disruptive, but it might not support your longer-term goals.
Launching a new line of business on a fresh platform can provide a contained way to learn before moving existing policies. Growing insurers feel this pressure most, and one Canadian brokerage CEO credits insurance technology at scale with helping his teams keep up as workloads grew.
The Evaluation Lens Leaders Should Use
Feature lists are long and often look alike. A short, weighted checklist keeps the discussion focused on business needs:
- Migration and parallel operation. How will policies move over, and can old and new systems run side by side?
- Product and rating configuration. Can analysts change rates and forms with appropriate testing and approval, or is development work required?
- Claims and billing depth. Do policy changes flow correctly into invoices, and can claims teams handle complex cases?
- Cloud design and integration. Can other systems exchange data through documented APIs, the software interfaces that connect applications?
- AI oversight. Can users review recommendations, trace their source data, and approve consequential decisions?
- Security and compliance. Can the platform demonstrate access controls, audit records, and support for your regulatory requirements?
- Implementation support. Are experienced partners and staff available for your products and region?
- Vendor stability and plans. Can the vendor support the platform long term, and which promised capabilities are available now?
Weight each item against business goals such as faster product launches, underwriting performance, or better service. A carrier launching new products may prioritize configuration; one focused on underwriting may give more weight to data quality and decision controls. Federato’s explainers on underwriting data and AI guardrails can help turn those priorities into specific evaluation questions.
What to Verify in a Modern Platform
Treat vendor announcements as prompts for testing, not proof of capability. Ask vendors to demonstrate the following in the version they are proposing:
- AI agents and approval controls. If software can take actions rather than just make recommendations, verify what it can change, who authorizes those actions, and how users review the record.
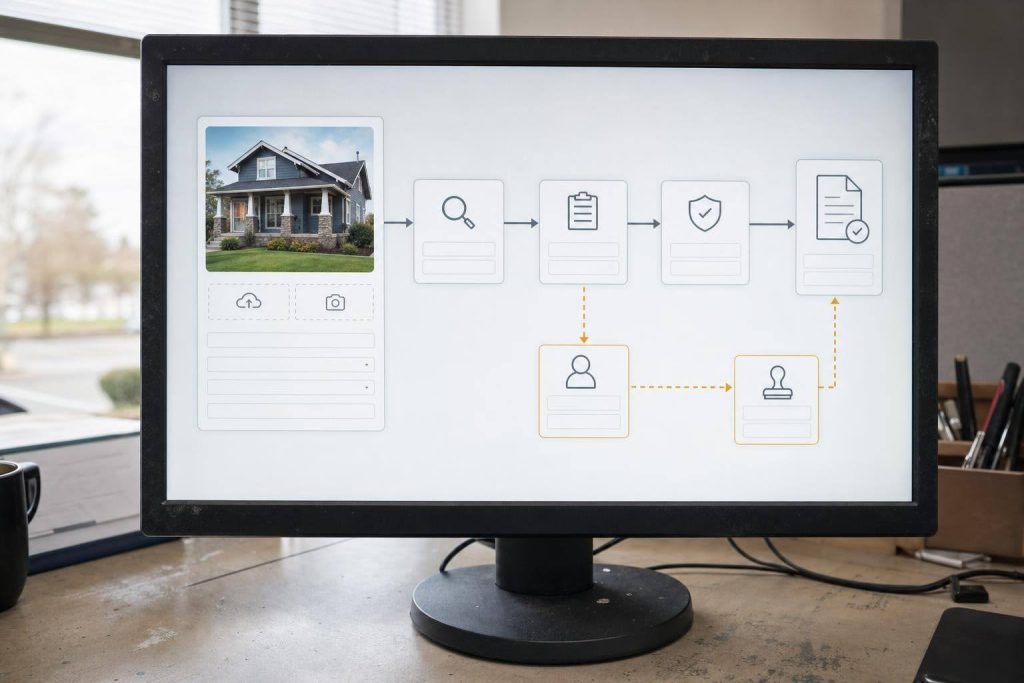
- Underwriting intake through policy issuance. Follow a submission through the workflow and identify where staff must re-enter data or switch systems.
- Usable workflows. Have a business user complete a routine task and handle an exception. Check whether required compliance and finance controls remain clear.
- Configuration effort. Ask what data, specialist work, and testing are needed to enable an AI feature in your environment. Separate a basic setup estimate from production readiness.
- Independent customer interfaces. Test whether customer and agent portals can change without extensive changes to the core platform.
Federato’s vendor-authored primer on insurance core systems offers a useful starting point for questions about shared data, AI-assisted underwriting, and approval controls. Use that vendor perspective alongside independent advice and demonstrations rather than as an exhaustive comparison.
Run Demos and Proofs of Concept Against Your Needs
Set the demo scenarios yourself. Use a demanding line of business and realistic, anonymized data, including legacy policies with unusual endorsements. Ask for three complete workflows: submission to quote, a policy change that affects billing, and an initial claim report through payment.
Require demonstrations of data conversion, rate filing support, and the upgrade process. For AI features, inspect the audit trail and any required human approvals. Before a proof of concept begins, define success measures, such as conversion accuracy, task completion time, and correct billing calculations. Record what was demonstrated and what remains a promise.
Implementation Risk, Budget, and Governance
Migration deserves as much scrutiny as product selection. Consider moving one line of business at a time and running old and new systems in parallel for a defined period. Document how transactions will be reconciled and when rollback remains possible. Confirm that experienced implementation partners and internal staff are available before signing.
Compare total cost of ownership, not license fees alone. Include subscriptions, any separate cloud charges, data conversion, integrations, upgrades, implementation services, training, and internal staff time. Establish a business and technology steering group with clear decision authority. Keep a shared risk log that records each issue, its owner, and the next action.
Red Flags and Traps
- Feature comparisons with no weighting for business goals
- Heavy customization that makes upgrades difficult
- Thin API documentation or reluctance to share it
- AI features with unclear data sources or approval controls
- Contracts without workable data export and exit provisions
- References limited to new launches, with no comparable legacy conversions
A 90-Day Planning Framework
Use this as an initial schedule, not a deadline that overrides due diligence. Weeks 1 to 2: agree on goals, scope, and weighted criteria. Weeks 3 to 6: issue a request for proposals and run scripted demos. Weeks 7 to 10: conduct a proof of concept against agreed measures. Weeks 11 to 13: complete reference calls, contract reviews, and partner assessments.
Allow more time where security reviews, procurement, or migration testing require it. Keep a decision log so future leaders can understand the evidence and tradeoffs behind the choice.
Selection Is a Risk Decision
The strongest choice is not necessarily the platform with the most features. It is the one that fits your business, can be migrated to safely, and can be governed over time. Independent advice, Federato’s core-system guidance, and your own scripted demos each contribute a different perspective. Base the final decision on demonstrated capabilities, realistic costs, and a credible delivery plan.
FAQ
Who should be on the selection team?
Include underwriting, claims, finance, IT, and compliance leaders, plus a sponsor authorized to make tradeoffs. Involve distribution leaders if agents or brokers depend on portals, and frontline staff who will use the system daily.
When do separate specialist systems make more sense than a full suite?
They may fit when a specialist function, such as underwriting or claims, needs capabilities the suite lacks, or when an existing system must stay. Assess the benefit against the added work of integrating systems, reconciling data, and coordinating support.
How long should the selection process take?
Use the 90-day framework as a baseline for criteria, scripted demos, a proof of concept, references, and review; add time for security, procurement, or migration testing.
How should leaders govern AI features?
Require clear data sources, human approval for consequential actions, audit records, access controls, and testing before production. Revisit those controls as workflows and models change.